Mortgage Protection
Life coverage planned around your home loan, so a benefit can help your family stay current on the mortgage or pay it down.
Henryville, Indiana · Clients nationwide
Desiree Garza helps families compare coverage for the mortgage, final expenses, income, and the rest of ordinary life. You get plain explanations, a pace that is yours, and a recommendation you can explain to someone you love.
How we start
Most households do not need every policy on a menu. They need one or two that match who they take care of and what they can spend. Desiree starts there, then shops the carriers she is appointed with through Gold Insurance Agency.
What we can look at
These are starting points for a conversation, not a promise that a particular policy is available or right for you. The contract from the issuing carrier is what controls the benefit.
Life coverage planned around your home loan, so a benefit can help your family stay current on the mortgage or pay it down.
A smaller permanent policy to help with a funeral and other last bills, instead of leaving that cost to your family.
A contract that can turn part of your savings into income payments. Desiree explains the term, the costs, and what happens to the money before you decide.
Pays benefits for covered injuries or death caused by an accident. Illness is not included, so this does not replace life insurance.
Permanent coverage with cash value that may earn interest tied to a market index, within the policy’s cap and floor. You are not investing in the market itself.
Lifelong coverage with level premiums and cash value that grows under the policy’s guarantees.
Protection for a set number of years, often while others rely on your paycheck. It usually costs less than permanent coverage and ends when the term ends.
Term coverage that can return the premiums you paid if you outlive the term and the policy conditions are met. The monthly price is higher than term without that feature.
Permanent coverage on a child that starts early and may include a way to buy more insurance later, even if their health changes.
Life insurance planned around a business loan, including an SBA loan, so a death benefit can help pay that debt. It is an insurance policy, not a loan from the SBA.
A plain-language comparison of Medicare options, including supplements and drug coverage where they are sold. This site is not part of Medicare, and you choose whether to enroll.
Help comparing individual and family health plans: monthly cost, deductible, and which doctors are in network. Choices depend on your state and the enrollment rules.
Descriptions are general. Premiums, benefits, and whether you can qualify vary by state, age, health, and the carrier’s underwriting.
Veteran families
A lot of Desiree’s appointments are with veteran households. She asks what coverage you may already have, then looks at private life insurance that can sit beside it — a mortgage, final expenses, income for a spouse, or a policy on a child.
She is not the Department of Veterans Affairs, and she does not file VA claims. This is insurance guidance for the family, at the pace you want.
Carriers
Desiree is an independent agent affiliated with Gold Insurance Agency. She is not on the payroll of one insurance company. When you ask for a quote, she looks at carriers she is appointed with and brings back options that match your health, your budget, and the state you live in.
The carrier has to be able to offer the benefit you asked for, in your state. A familiar name is not a reason to skip the comparison.
Age, health, and the type of policy change the price and sometimes the offer. You see that before you apply, not after you have signed.
You still talk with Desiree. She is the one who explains the differences and stays available after a policy is issued.
Carrier names come up when there is a real quote to review. Appointments can change, and not every company offers every product.
About
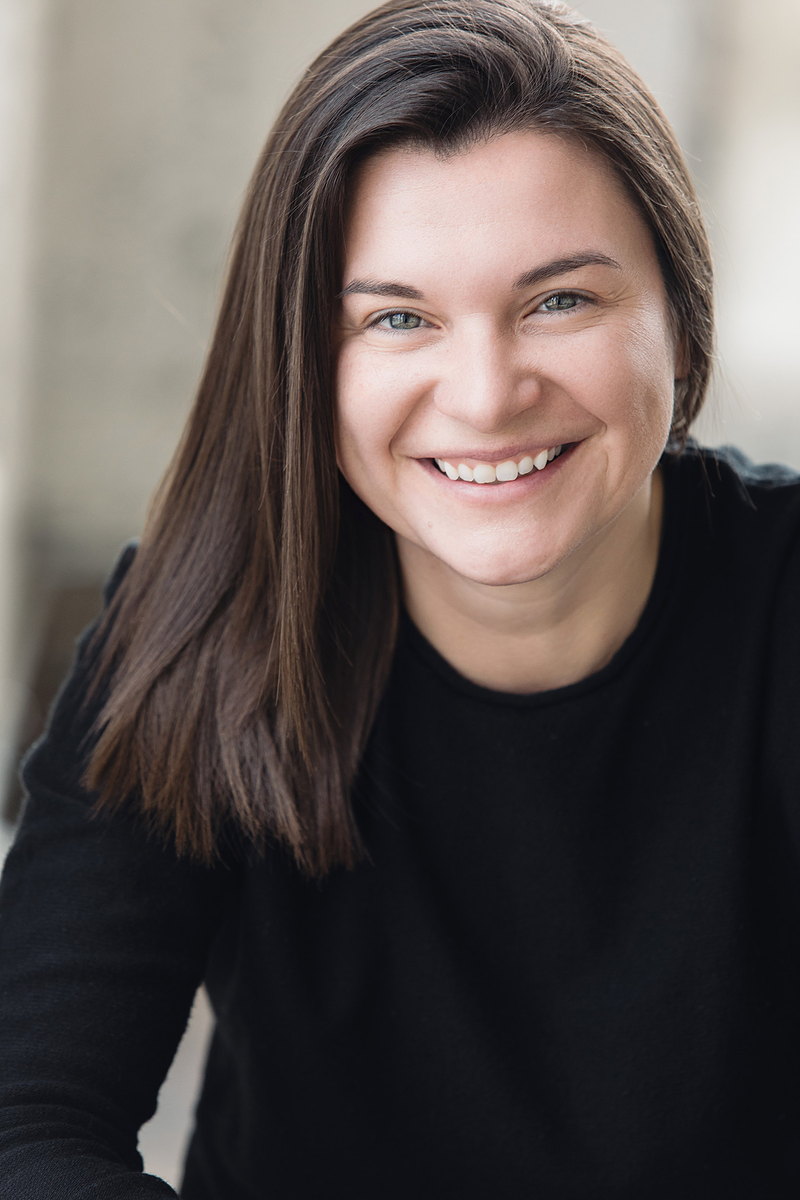
Desiree Garza lives in Henryville, Indiana, and she talks with families the way she would want someone to talk with hers. The explanations are plain. The pace is yours. Nothing is dressed up to sound more certain than it is.
She is affiliated with Gold Insurance Agency, which lets her look past a single company when she shops for coverage. You do not have to live nearby. Meetings are by phone or video, anywhere she is able to write the policy.
If you cannot explain the policy to your family, it is not time to buy it.
If something is a poor fit, she says so — including when the better answer is to keep what you already own.
Phone and video appointments for clients across the country. A product can still be limited by state, carrier, and underwriting.
Questions show up after a policy is issued. Desiree helps with service, beneficiary updates, and reviews when life changes.
How working together goes
A phone or video call about your family, coverage you already pay for, and a monthly number that feels realistic. There is no fee for the conversation.
Desiree brings back policies in plain language: what they pay, what they cost, and what they leave out. You will know the carrier before you apply.
Apply only if the coverage makes sense. If you move ahead, she helps with the paperwork and stays available after the policy is in force.
Contact
Call, email, or send a note. Desiree reads these herself and follows up by phone or email. Asking for a conversation does not start an application, and it does not lock you into a policy.